 Megan Banta
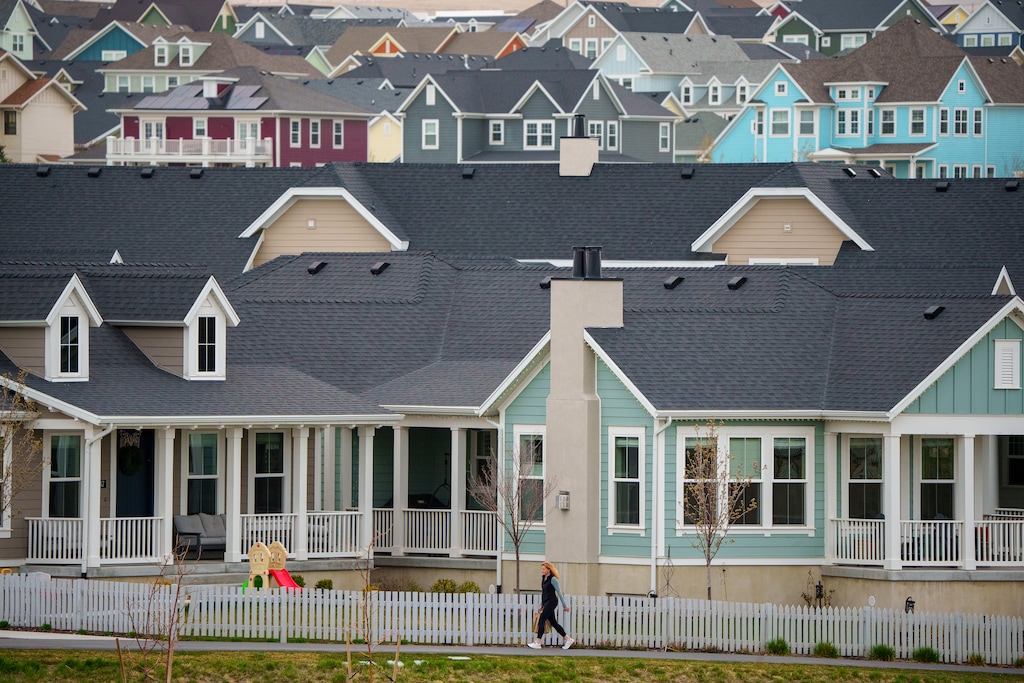
Utahns need to make slightly less to purchase a home than they did last year, but the state’s homebuying picture remains far from rosy.
Overall, the market is “bleak” for most people looking to get their first home, according to a new report from the Kem C. Gardner Policy Institute.
So, what’s keeping people out? Utah still ranks among the most expensive states for home prices, interest rates are high, and a mortgage payment is about twice as much as a decade ago.
That could create challenges down the road if an entire generation is locked out of the stability and wealth generation that ownership offers, said Steve Waldrip, who heads the recently created state Division of Housing and Community Development and advises Gov. Spencer Cox on housing strategy
Waldrip and a group of housing experts at a panel discussion this week pointed to some possible solutions, including smaller houses on smaller lots, more state money for roads, sewer and other infrastructure, and creative financing arrangements.
More affordable, but hard to enter the market
Utah’s median home price from January to March was $544,000, the 10th highest in the country, according to data from the National Association of Realtors.
The Utah Association of Realtors puts the price slightly lower at $520,000. Either figure is more than double the typical price of a home a decade ago.
Even though housing prices are up, homes technically are more affordable. It took a household income of $149,000 to afford a home at the middle of the market in 2025. That’s down a tick to $147,000 this year.
Someone’s salary isn’t the biggest barrier, though, said Steven Bond, who founded the nonprofit HomeOwnership4U. The typical down payment to buy a home is $119,000, he said — and some sources put it at more than $200,000 in Utah.
High prices and mortgage rates also mean monthly payments have jumped. When interest rates were lower from 2018 to 2021, monthly principal and interest on a loan was between $1,300 and $1,700, according to the report.
It “shot up” after that, said Dejan Eskic, a senior research fellow at the Gardner Institute whose focus includes housing.
For the past two years, principal and interest have averaged more than $2,900 a month, according to the report, and is down slightly this year to $2,875.
No longer is it enough to get an education, work hard and save for a home, Bond said. That could have dire implications, the panelists said Wednesday.
“If you have a generation without wealth, what does the world look like in 20, 30 years?” Eskic said.
Build smaller
There are some possible solutions to make sure that doesn’t happen, all four men on the Gardner Institute panel said — and the biggest one is actually little.
“We know that the things that are affordable today are small things on small lots,” Waldrip said, but market forces remain a barrier to that.
Even in cities that allow smaller lot sizes, Eskic said, developers are still building homes that are between 3,000 and 4,000 square feet.
“They know the move-up buyer will come, but they’re not necessarily sure if the starter-home buyer will come,” he said.
Troy Fitzgerald, the city administrator for Springville, confirmed that setting land up for small homes doesn’t necessarily mean developers will build them.
The city just southeast of Provo has more than 2,000 lots available with less than 3,000 square feet, he said, and “very, very few” have homes being built. Where there is construction, he said, the home often takes up most of the lot.
There are ways to change that, panelists said, like speeding up the planning process, having pre-approved plans or having the state help to build a model for smaller home developments.
Market is ‘gummed up’
Supply, costly homes and high interest rates have “gummed up” Utah’s market, Fitzgerald said.
People don’t want to give up their 3% interest rates from when they bought between 2020 and 2022, but they shouldn’t expect rates to return to that, Waldrip said.
Some countries in Europe allow people to take their mortgage with them when they move, which “would be one of the biggest game changers” if the U.S. adopted it, he said.
Waiting for interest rates to drop is likely to backfire, Eskic said. There is no guarantee rates will drop, but the costs of labor, materials and land will certainly rise, he said.
Eskic said he expects the market to be stubborn during the next decade.