 Leia Larsen
Note to readers • This story is made possible through a partnership between The Salt Lake Tribune and Grist, a nonprofit environmental media organization.
In just a few years, Utah cities, counties and state agencies have created hundreds of quasi-governmental agencies led by unelected boards that approved billions of dollars’ worth of debt.
That has State Auditor Tina Cannon concerned. She invited representatives of the U.S. Securities and Exchange Commission to help Utah municipalities understand what’s at risk as public infrastructure districts, or PIDs, pop up in every corner of the Beehive State.
Developers may mislead local governments by asserting PIDs are the only way for important projects to get funded, Cannon and the SEC officials said. Cities and counties that approve them may see hits to their credit ratings. Homebuyers are getting saddled with unexpectedly high tax rates to help pay off all the builders’ borrowing.
And, ultimately, having so many tax-levying agencies with unelected boards inherently creates risk, federal regulators warned.
“We’re agnostic” about PIDs, said Dave Sanchez, the SEC’s municipal securities director, in an interview. “But what I would think would be interesting for most taxpayers is who’s making this decision that is potentially raising our taxes for the future, and what access do I have that influences that decision if I’m not happy with it?”
Utah lawmakers allowed for formation of PIDs starting in 2019. The idea was to create mechanisms for developers to finance public projects like roads, sidewalks and water pipelines. The developers take on bonds to build that infrastructure, then pay back the debt by collecting additional property taxes within the boundaries of the districts that benefit from them.
Lawmakers added infrastructure financing districts in 2024, which are governed by a different state code, but are similar enough to PIDs that they’re often lumped together.
In seven years, about 250 of these districts have popped up across the state, which Sanchez called “impressive.”
He also told local government representatives that all the PIDs have “real potential to become a problem if not handled correctly.” He spoke to them Monday, during a transparency conference hosted by the State Auditor’s Office.
PIDs have been tapped to help finance rail infrastructure for the Utah Inland Port Authority and luxury real estate at ski resorts with support from the Military Installation Development Authority (MIDA). They’ve been leveraged by the developers building Utah City, Vineyard’s new downtown, and to redevelop the Delta Center area in Salt Lake City. Many are used to build subdivisions.
“They’re also one of the No. 1 topics for hotline complaints over misuse” submitted to the auditor’s office, Cannon said in an interview.
A local government must sign off on the PIDs, but their bonds are typically governed by the developers themselves, who usually start out as the sole property owners before the parcels are subdivided and sold. Still, PIDs must comply with transparency laws required by other government agencies, like providing advance notice of board meetings and posting budgets, since they manage taxpayer money.
Less than half of the state’s PIDs are in compliance with state transparency requirements, Cannon said. But they’ve already issued $5.3 billion in debt. That’s up from $3.6 billion just a year ago. Cannon’s office expects the debt to balloon to $13.8 billion when the 150 not-yet-bonded PIDs obtain financing.
At the current clip, the auditor projects there could be 500 more PIDs formed in Utah over the next decade, which her office expects will issue $44.9 billion in debt.
Who assumes the risk?
PIDs are attractive to developers because they’re able to get loans at lower interest rates, since they’re backed by governments and deemed less risky.
But developers sometimes falsely assert PIDs are the only mechanism to pay for their infrastructure projects, Cannon and Sanchez said.
“We hear from municipalities that they’re being told ... ‘this is what we want, and this is what we want you to use,’” Cannon said. “They feel like they have no choice.”
Those local governments are entitled to refuse, Cannon said. If developers pressure local governments about financing, they also run the risk of violating federal law, Sanchez said.
“If you’re recommending a PID, then you’re recommending bonds,” Sanchez said. The SEC considers people who make such recommendations “municipal advisers,” who must register with the agency.
The SEC doesn’t enforce PIDs’ compliance with state code. It mostly regulates how governments communicate with investors, Sanchez said. That doesn’t mean PIDs aren’t cause for concern at his office.
“These unelected boards have the ability to issue bonds, impose taxes and pass those costs onto taxpayers in your state,” Sanchez said. “That is going to create some unique kinds of risks.”
Other quasi-governmental state development agencies, like MIDA and Utah Inland Port Authority, have the ability to form PIDs as well. MIDA and UIPA boards are also appointed rather than elected, and their members have included state lawmakers, lobbyists and developers.
Sanchez declined to say whether these governance structures are “inherently good or bad.”
“You’re one further step removed from the people who are directly accountable to taxpayers,” Sanchez said. “That’s the part that creates elevated risk.”
State development authorities like MIDA, UIPA and Point of the Mountain State Land Authority can also collect sales tax to repay bonds. Sanchez called that surprising, and said few other states allow it.
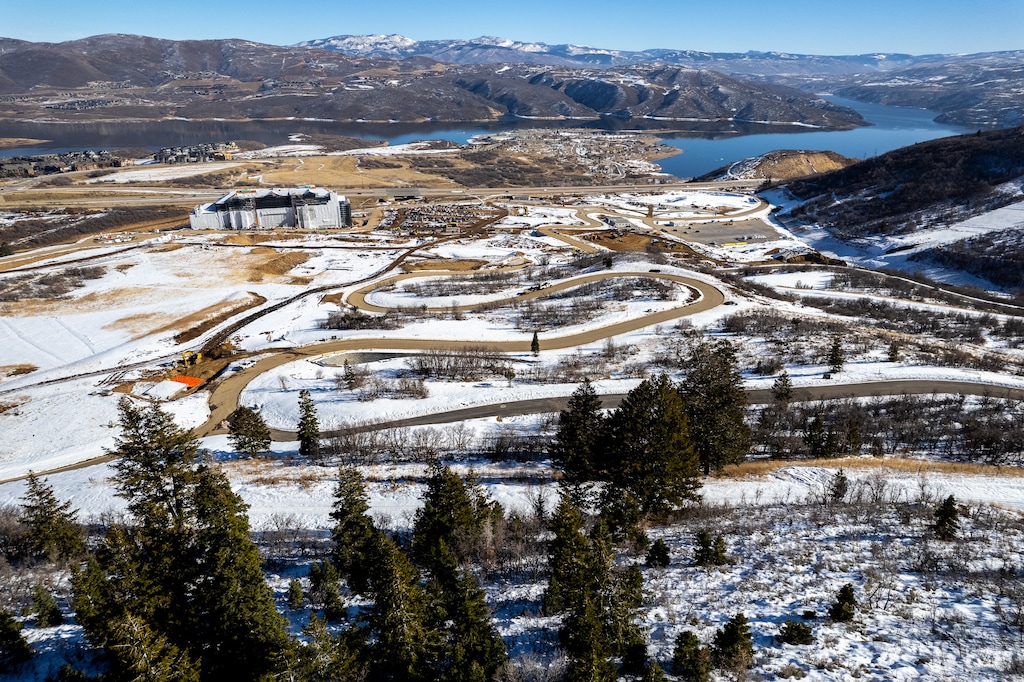
(Rick Egan | The Salt Lake Tribune) The Inland Port Authority is one of dozens of government agencies in Utah that has created public infrastructure districts, allowing developers to take on debt to build things like pipelines, roads and rail. One of these PIDs covers the port authority's jurisdictional areas in Salt Lake City's northwest quadrant, seen on Tuesday, December 26, 2023, and allowed developers in the area to tap $150 million in bonds.
Layering debt
Under state law, PIDs can levy $1.50 per $1,000 of value in property taxes, compared to $4 for school districts and $2 for counties. But multiple PIDs can also tax the same parcel, according to information from the State Auditor’s Office.
That means a homeowner may pay more in taxes, because their property falls within multiple PID boundaries, than a neighboring subdivision – sometimes substantially more.
“You really have a hidden second mortgage payment,” Cannon said.
Bonds often take 30 to 40 years to repay, she added.
One homeowner of an apartment at the Black Desert resort in St. George pays property taxes of $10,000 a year due to PIDs, as reported by the Utah Investigative Journalism Project. But buyers typically aren’t aware of these additional costs until closing.
Local governments that approve PIDs usually aren’t liable if the PIDs default on their bonds, but that doesn’t mean there aren’t consequences. The Great Recession of the 2000s saw developers go belly-up, leaving cities with unfinished infrastructure and zombie subdivisions.
“Big picture, it becomes an issue because people lose faith in the market,” Sanchez said.
And layered debt brought by PIDs can mean the cities, counties or other governments get flagged by credit rating agencies, harming their ability to borrow in the future.
“They have to consider the overall debt burden that already exists on the taxpayer,” Sanchez said. “It’s a very real concern ... that debt burden can affect taxpayers’ willingness to be taxed more.”
Cannon said she has heard anecdotal reports that real estate agents in Utah now encourage buyers not to purchase properties in PIDs, or outright refuse to show homes that lie within them.
Utah’s PIDs are relatively young, but in other states where similar financing structures run by private citizens are decades old, the SEC runs into issues when local governments forget they exist. In some cases, the boards have paid for-profit agencies and part-time “employees” millions of dollars each year essentially to do nothing, Sanchez said.
Another common violation SEC sees with PID-equivalents in other states is that the developers and private citizens on governing boards don’t properly disclose conflicts of interest. Sanchez said he reviewed a sample of Utah’s PIDs and found no disclosure issues.
A primary concern for Cannon, however, is that local governments approve PIDs with the expectation that the cheaper financing tool will give builders an incentive to construct more affordable housing for their communities. But local governments, so far, don’t have a good way to track whether the savings from less expensive loans actually get passed on to future homebuyers and renters.
“Nothing’s impossible to measure,” Cannon said. “However, the reality is: it’s not part of the of the discussion at this point in Utah.”